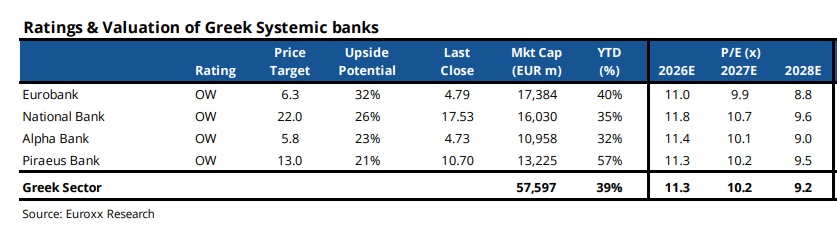
Greek banks continue to trade at a discount to their European peers, despite superior credit growth, strong domestic macroeconomic figures, higher ROTE and better returns to shareholders, a Euroxx analysis notes.
Taking these superior fundamentals into account, we believe that Greek banks should trade at a premium to their peers and we further upgrade our target prices by about 20%, due to earnings estimate upgrades and higher relative valuations. We are positive on all four systemic banks, but we see the greatest upside in Eurobank, given its lower P/E ratio and strong growth prospects in the region.
Sustainable growth in bottom-line profitability by about 10%.
We have further upgraded our forecasts for Greek banks by mid-single-digit levels, following the strong results of the second quarter of 2026 and higher interest rates, the report notes.
The key theme for Greek banks remains credit growth and the effort to increase revenues outside net interest income (non-NII). In our view, the long-term prospects for credit growth remain positive, driven by the corporate sector and with the first signs of recovery in mortgage lending.
Healthy growth in fee income will also support a strong compound annual growth rate (CAGR) in net profits, of about 10%, through 2028E.
EPS upgrade, higher target prices
We have upgraded our net profit forecasts by mid-single-digit levels for 2026 and believe that, going forward, risks are tilted to the upside, due to higher interest rates and the steady outperformance of the Greek economy.
We believe that the fair value of Greek banks corresponds to a range of about 13x P/E for 2027, that is, about a 15% premium to European peer banks. Overall, we remain positive on the sector and have high conviction in our earnings forecasts for the 2026-28 period.
- Specifically, for the National Bank (NBG), the target price is raised to 22.0 euros, from 19.4 euros previously, versus the latest closing price of 17.5 euros.
- For Eurobank, the target price is upgraded to 6.3 euros, from 5.3 euros, with the latest closing price at 4.8 euros.
- For Piraeus Bank, the new target price amounts to 13.0 euros, from 11.0 euros previously. With the latest price at 10.7 euros, the upside is estimated at 21%.
- Finally, for Alpha Bank, the target price is raised to 5.8 euros, from 5.2 euros, versus the latest closing price of 4.7 euros.