Greece offers one of the most attractive banking markets in Europe, supported by investment-driven GDP growth and by some of the highest rates of credit expansion in Europe.
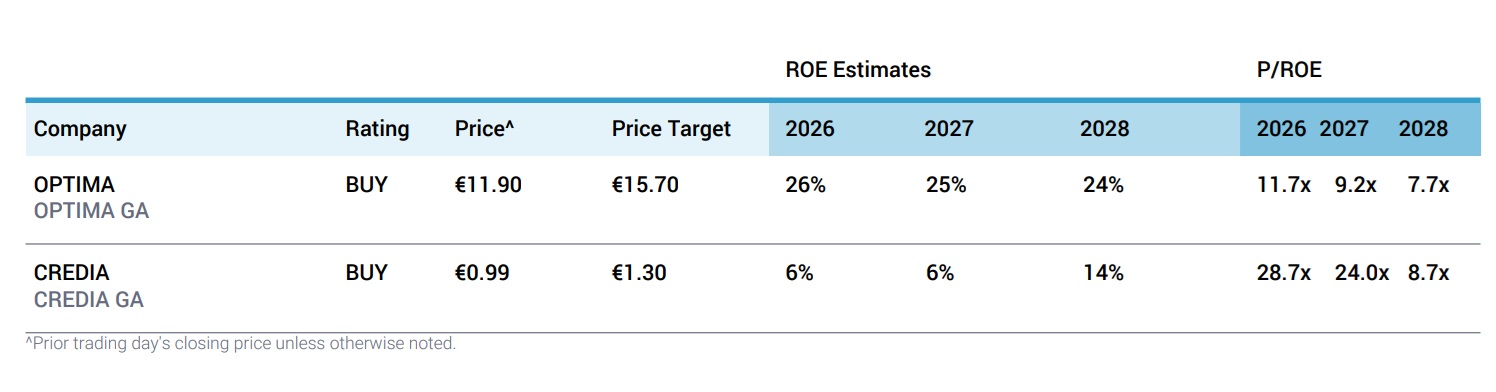
OPTIMA and CREDIA offer exposure to this opportunity through two different models. We initiate coverage of both banks with a BUY recommendation, for different reasons, Jefferies writes in its analysis. We consider OPTIMA (target price 11.9 euros) a high-quality bank with the ability to compound growth, while CREDIA (target price 0.99 euros) a transformation story in the banking sector, with significant potential for earnings growth.
Attractive macroeconomic environment and growth opportunities for the banking sector:
Greece offers one of the most attractive banking growth opportunities in Europe. GDP growth is expected to exceed the EU average throughout the forecast period, supported by improving public finances and European funds.
The increase in corporate financing is among the highest in Europe, while investment spending continues to rise. SMEs remain an underserved sector and are a key pillar of the Greek economy. The focus on SMEs is the main growth driver for both OPTIMA and CREDIA.
A bank with the ability to compound growth and a transformation story:
In this environment, we initiate coverage of Greece’s two challenger banks, OPTIMA and CREDIA. Although both institutions are gaining market share thanks to their greater focus on SMEs and small businesses compared with established banks, the investment cases are fundamentally different and offer investors EPS growth significantly higher than that of the European banking sector.
OPTIMA – high-quality bank with the ability to compound growth:
Based on a clean balance sheet, an operating model led by Relationship Managers, and a focus on high-income clients and SMEs, the bank posts some of the best KPIs among all EU banks.
Growth is exclusively organic, with no burden from legacy NPEs, allowing management to focus exclusively on growing the bank. Higher-yield SME lending, effective deposit gathering, and an increasingly diversified fee income ecosystem support returns that already rank among the highest in Europe.
CREDIA – transformation story:
After years of restructuring, reducing NPEs and rebuilding its capital base, the bank has completed its recovery and is now focused on growth. The merger with Pankritia created Greece’s fifth banking pillar, while acquisitions in insurance, brokerage, and wealth management are transforming the business into a broader financial services platform.
Most importantly, HSBC Malta adds scale, provides lower-cost funding, surplus capital, capabilities in the insurance sector and wealth management, as well as a second growth market for the group, while doubling the asset base. From 2028 onward, a significant acceleration in earnings and ROTE is expected to levels comparable to those of the European banking sector.
Same exposure, but different starting points:
Both banks offer exposure to the same structural opportunity, but from a different starting point. OPTIMA offers high returns already today, supported by a proven business model and strong execution. CREDIA offers greater room for future return expansion, as management leverages its scale, integrates acquisitions, and broadens sources of profitability beyond traditional lending activities.
Valuation – Higher ROTE and EPS growth than the sector, while the stocks trade at a discount:
We forecast ROTE of 24% and 18% in 2028 for OPTIMA and CREDIA, respectively, versus 18% for the European banking sector. OPTIMA offers EPS CAGR of 24%, about double the sector average, while CREDIA records even stronger earnings growth, supported by HSBC Malta.
Despite superior growth and profitability, both stocks trade below the European banking sector, at a discount of about 15% versus the European banking sector in P/E terms.