Two of the most recognizable listed companies in the Greek market, Athens International Airport (DAA) and Autohellas, recently published their results for the first half of 2026. Both companies display the same basic characteristic: operating activity that is either increasing or holding at good levels, while final profitability is being squeezed by increased depreciation accompanying their extensive investment programs.
Below we present the results and our valuation, with a target price for each stock.
Athens International Airport (DAA)
Results for the first half of 2026
According to the figures published by the company, passenger traffic at "Eleftherios Venizelos" amounted to 15.8 million passengers in the first half of 2026, up by 4.5% compared with the corresponding period last year, with domestic and international traffic exceeding last year's levels by 5.1% and 4.2% respectively.
Despite the increase in traffic, the financial figures declined: total revenue and other income fell by 2.8% to €299.6 million (from €308.2 million), mainly due to the temporary 30% discount on the Passenger Service Charge that was applied from October 1, 2025 to April 30, 2026.
Adjusted EBITDA came to €168.5 million, down 7.6% (margin 56.2% versus 59.2% last year), while profit before tax fell by €13.6 million to €106.6 million and net profit by 11.6% to €81.4 million, from €92.2 million.
Fees and third-party expenses were particularly increased (+15%), while utility expenses, by contrast, fell by 37.3% thanks to the energy-saving initiatives of the "Route 2025" program.
Management upgraded its forecast for passenger traffic to a mid-single-digit growth rate for the whole of 2026 (from low single-digit previously) and confirmed the target for net profit of around €200 million for this year, with a commitment to distribute 100% of distributable profits.
At the same time, it announced a revision of the expansion program: total capital expenditure through the end of 2030 is now estimated at €950 million (2026 prices), with more phased and flexible implementation.
The net debt to EBITDA ratio is expected to move between 2 and 3 times during the investment period, without exceeding 3.5 times — a target which, combined with the €806 million bank loan secured in 2024 and the €500 million bond issued in June 2026, covers the company's financing needs through 2030.
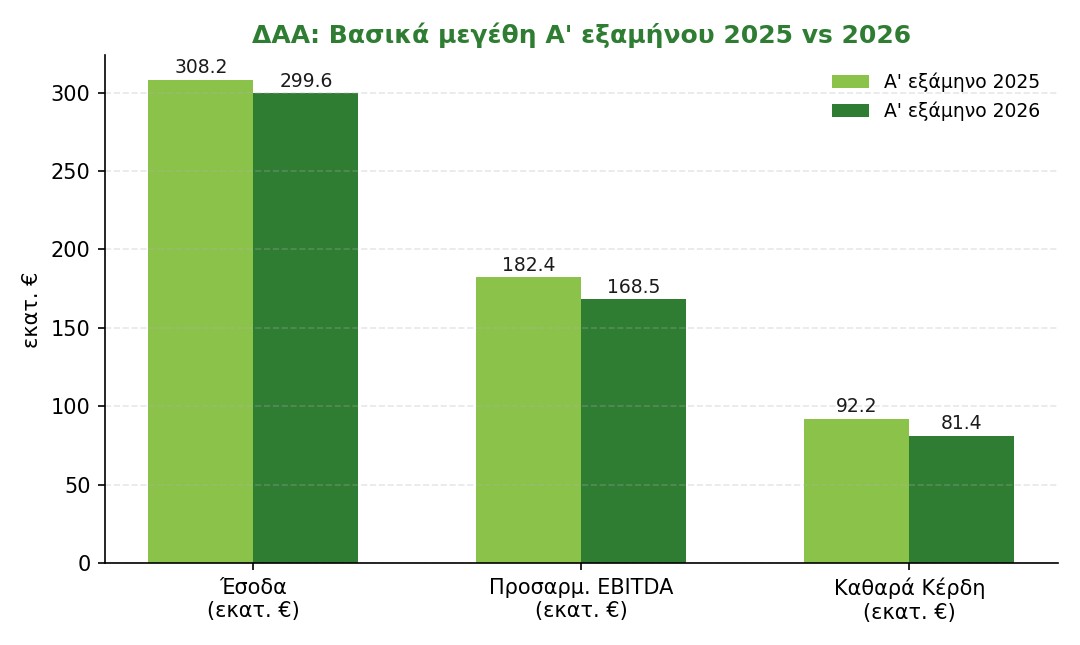
DAA financial figures
First half, compared with first half 2025 (amounts in € million)| Figure (€ million) | first half 2025 | first half 2026 | Annual change % |
|---|
| Passengers (million) | 15,1 | 15,8 | +4,5% |
| Revenue | 308,2 | 299,6 | -2,8% |
| Adjusted EBITDA | 182,4 | 168,5 | -7,6% |
| Profit before tax | 120,2 | 106,6 | -11,3% |
| Net profit | 92,2 | 81,4 | -11,6% |
| SOURCE: DAA | |
The valuation model: regulated asset base (RAB) / WACC
For DAA we apply the same valuation framework that we use for other regulated assets: aviation profitability is by design limited to a return of about 15% on the inflation-adjusted regulatory asset base (Regulatory Asset Base).
This means that DAA is not a "traffic-beta" story — passenger growth does not pass proportionally into earnings — but a regulated equity story with a commercial overlay (retail, food service, parking), where operating leverage is unlimited.
We apply the two-stage dividend discount model (DDM) approach: cost of equity at 9.0% (consistent with the BBB+ credit rating profile and the country risk premium after the upgrade of the Greek market to Developed Market); with estimated 2026 dividend at €0.60/share and dividend growth rate at 4.5% annually through 2035, in line with market estimates for 2027-2035 earnings CAGR (aviation sector +3.3%, non-aviation +5.8%); and long-term growth rate of 2.0% from 2036 onward.
The result gives a value of about €10.05-10.10 per share.
As a cross-check we apply a 10x multiple to estimated 2026 EBITDA (about €393-394 million, practically stable compared with 2025), subtracting net debt. Given that management targets a net debt/EBITDA ratio between 2x-3x during the investment period, this method gives a value range from about €8.70 to €9.90 per share at the lower-upper end of the targeted leverage ratio — an indication that the cost of the investment program somewhat pressures equity value downward relative to the pure DDM approach.
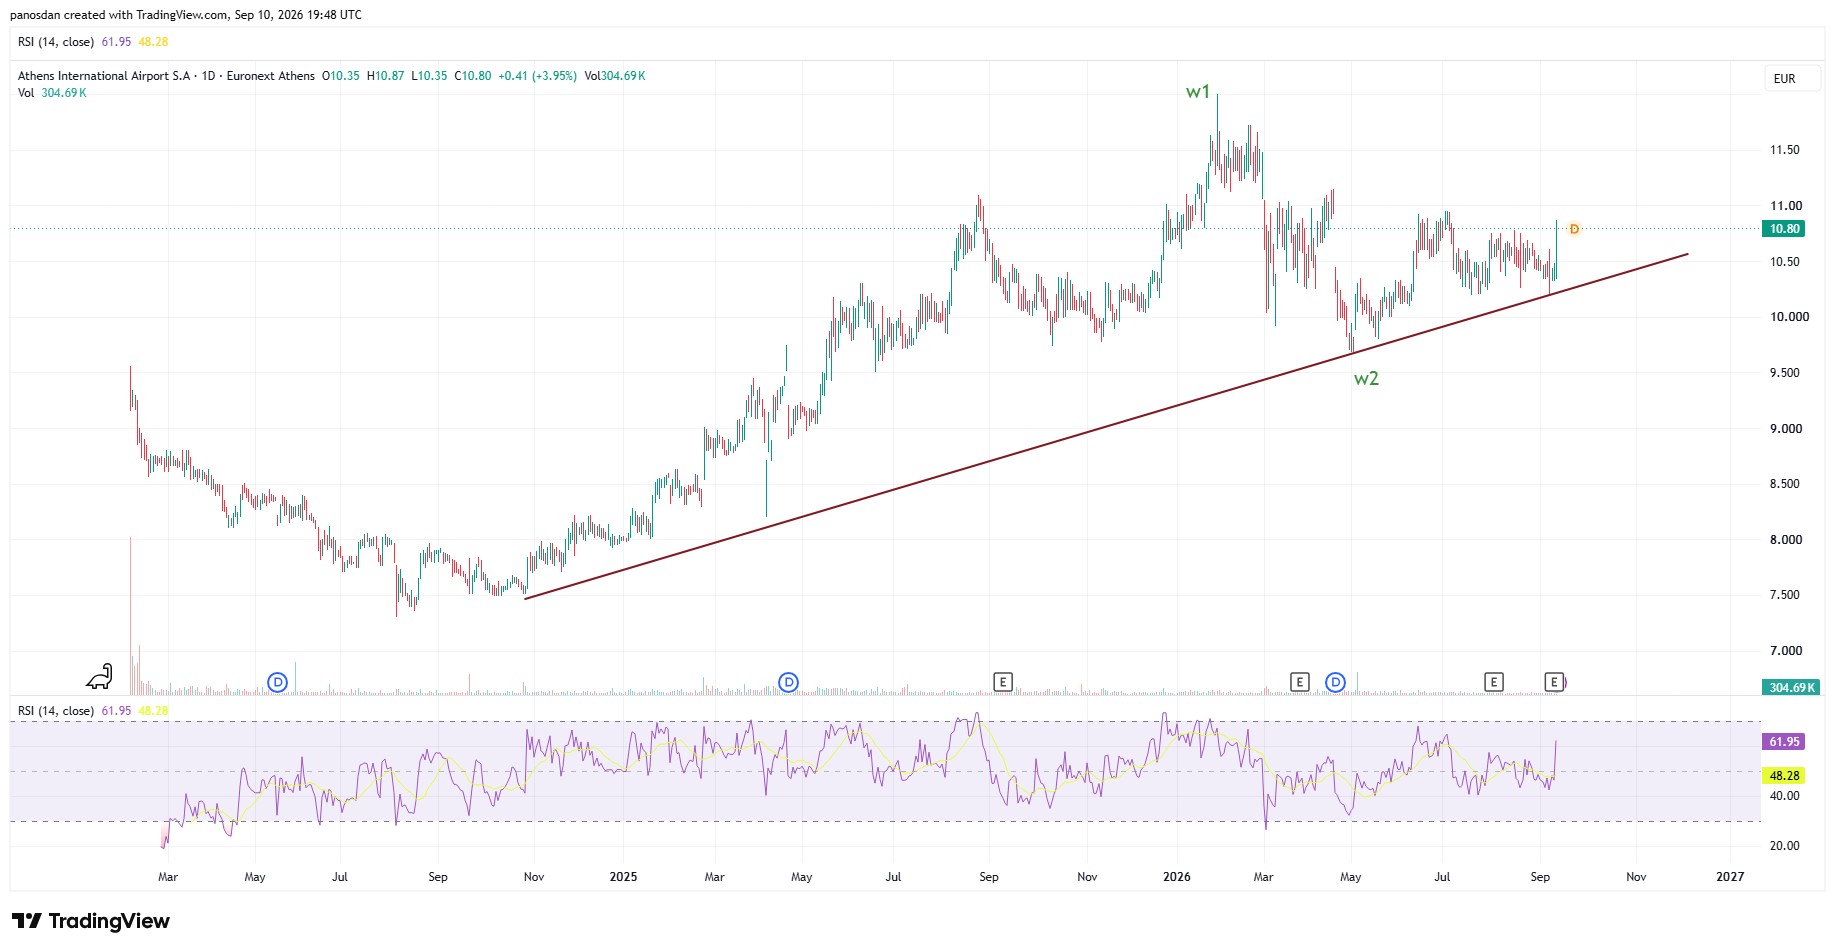
DAA valuationDAA target price: €10.20 | Recommendation: HOLD Current price: €10.68 (10/9/2026) — Market capitalization: €3.40 bn. The stock is trading close to its fair value. With a dividend yield of about 6%, the total expected return remains marginally positive. |
| |
The case of Autohellas
Results for the first half of 2026
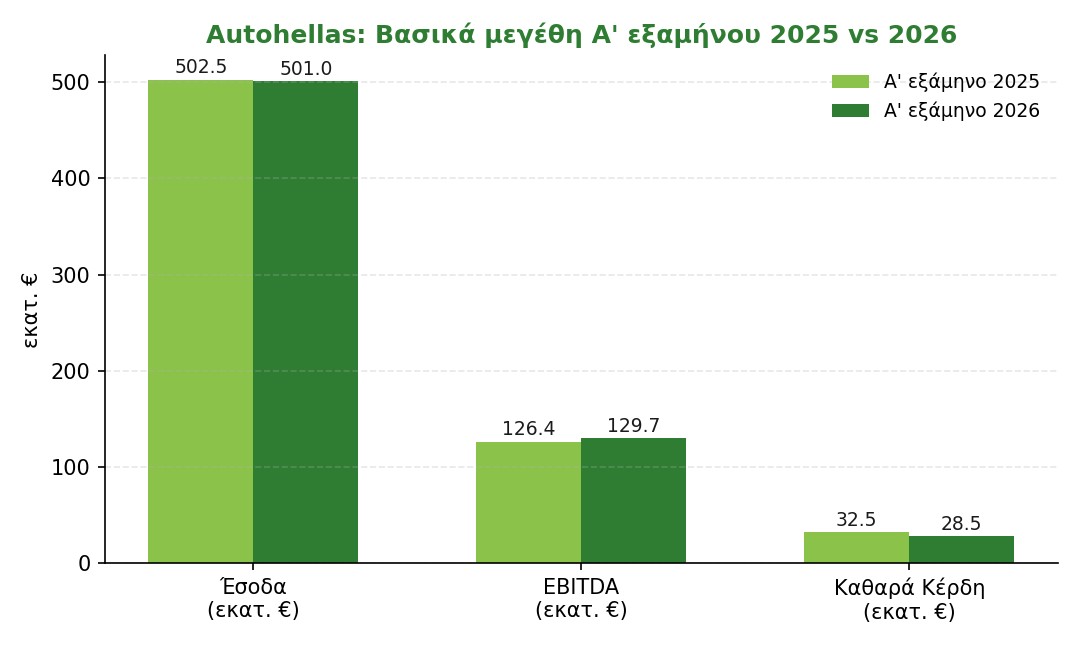
According to the company's Half-Year Financial Report (approved by the Board of Directors on September 8, 2026), consolidated turnover amounted to €501.0 million in the first half of 2026, marginally down by 0.3% compared with the first half of 2025 (€502.5 million).
EBITDA increased by 2.6% to €129.7 million, but operating profit (EBIT) fell by 20.1% to €33.3 million and net profit declined by 12.3% to €28.5 million — a divergence due almost exclusively to increased fleet depreciation (€96.4 million versus €84.8 million), resulting from investments in about 13,400 new vehicles during the half-year.
By activity, car rentals in Greece (Hertz) increased their revenue by 6.7% to €146.6 million, driven by long-term rentals due to increased demand from corporate clients.
International rental activity recorded revenue growth of 10.6% to €87.3 million, with Portugal contributing the largest increase, although it remained loss-making due to seasonality, while activity in Cyprus was burdened by geopolitical uncertainty in the Middle East in the first five months.
By contrast, car trading and services in Greece recorded a 6.6% drop in revenue to €267.2 million, mainly due to the Hyundai/KIA model cycle and of course the growing presence of new — mainly Chinese — models in the Greek market.
The Group's equity amounted to €556.5 million on 30.6.2026, while net debt came to €822.7 million (from €789.7 million at the end of 2025), giving a gearing ratio of 1.48x — within the targeted 1x-2x range set by management. After the close of the half-year, in July 2026, the company increased the existing securitization agreement by €80 million, bringing the total financing framework to €370 million.
Autohellas financial figures
First half 2026, compared with first half 2025 (amounts in € million)| Figure (€ million) | first half 2025 | first half 2026 | Annual change % |
|---|
| Revenue | 502,5 | 501,0 | -0,3% |
| EBITDA | 126,4 | 129,7 | +2,6% |
| EBIT | 41,6 | 33,3 | -20,1% |
| Net profit (EAT) | 32,5 | 28,5 | -12,3% |
| Net debt (end of period) | — | 822,7 | — |
| SOURCE: Autohellas | |
The valuation model: EV/EBITDA and P/E
For Autohellas we apply a combination of the EV/EBITDA multiple (main method for an asset-intensive sector such as car rental) with a cross-check via P/E.
Based on the growth rate of the first half and the traditionally stronger contribution of the third quarter (about 53% of short-term rental revenue in Greece is generated in July-September, according to the company itself), we estimate 2026 full-year EBITDA at about €303 million (+2.8% versus €294.7 million in 2025) and net profit at about €78-79 million (versus €84.0 million in 2025), as the compression trend from depreciation is expected to continue.
Applying a 5.0x multiple to estimated 2026 EBITDA (€303 million) results in an Enterprise Value of about €1,515 million, from which we subtract net debt of €822.7 million (30.6.2026, as published in the Half-Year Report), arriving at an equity value of about €692 million or €14.25 per share.
The cross-check via P/E (9x-10x on estimated 2026 earnings per share of about €1.50-1.55) gives a range of €13.50-15.00 per share, confirming our methodology.
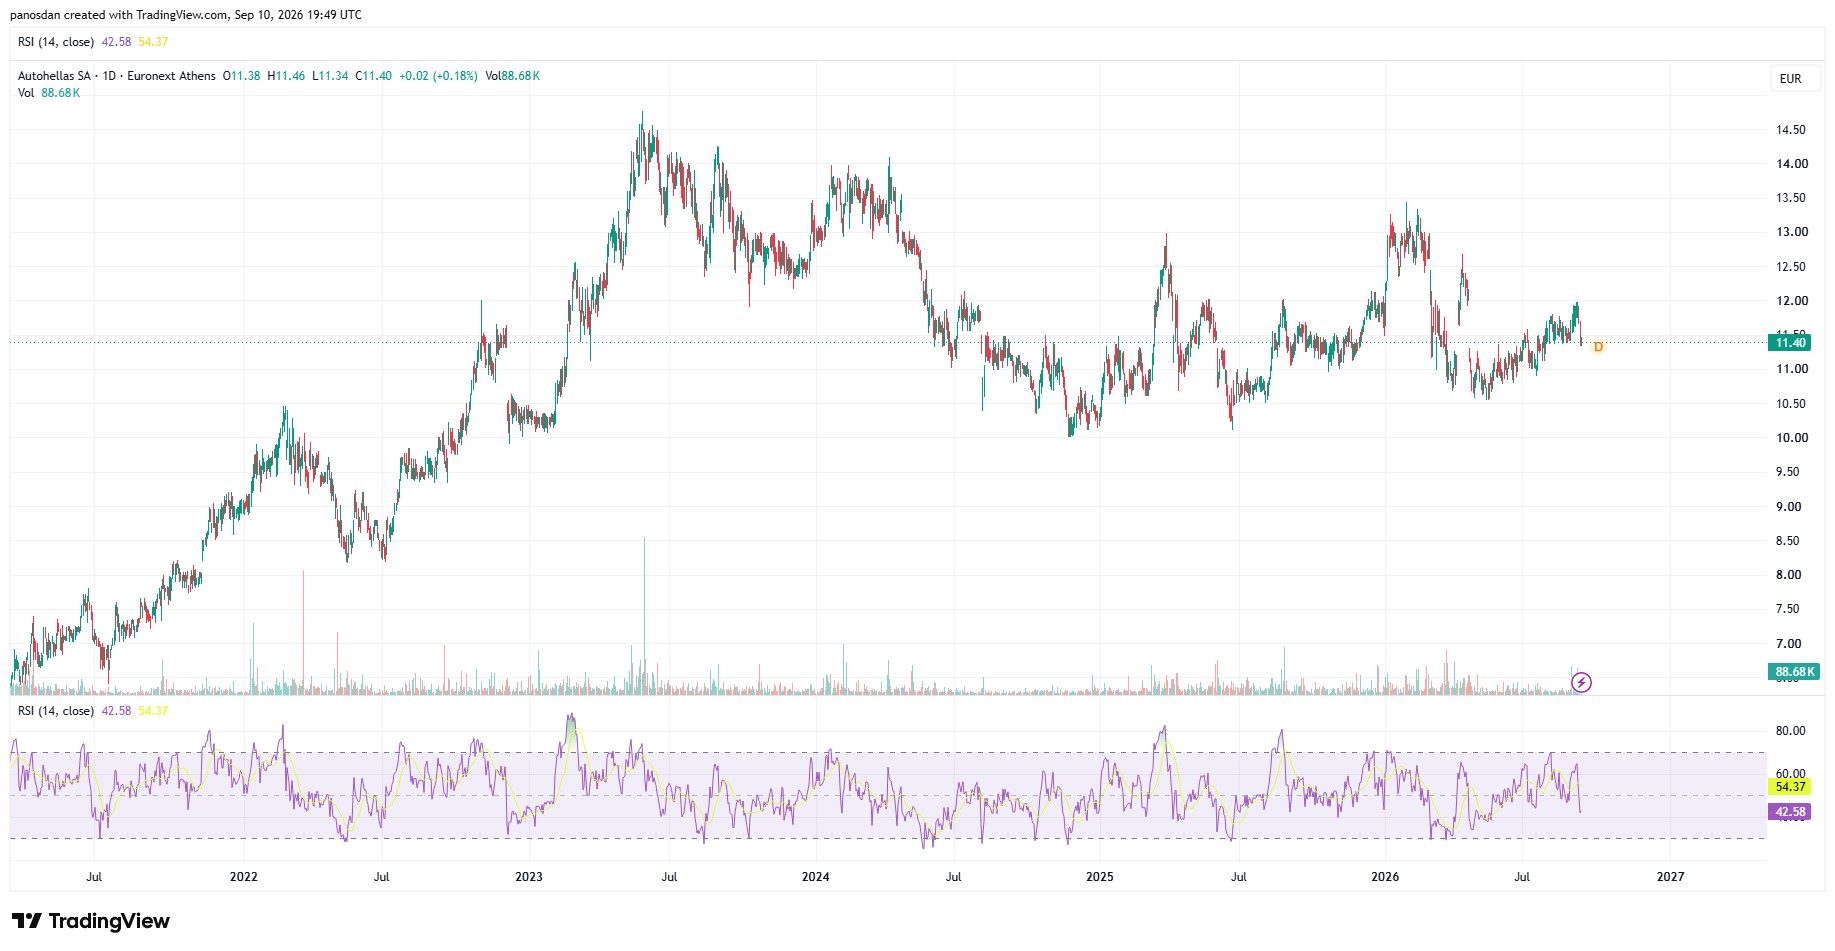
Autohellas valuationAutohellas target price: €14.00 | Recommendation: BUY Current price: €11.40 (10/9/2026) — Market capitalization: €554.3 million. Upside potential of about 23% from current levels, with a dividend yield of 7.4% (€0.85/share for fiscal year 2025) adding attractiveness. Main risk: if the fleet depreciation rate continues to "eat into" net profit faster than EBITDA growth, the P/E multiple will remain under pressure. |
| |
In summary
Comparison of valuations & recommendations| Company | Price (10/9) | Target price | Upside/Downside | Recommendation |
|---|
| DAA | €10,68 | €10,20 | -8,3% | HOLD |
| Autohellas | €11,40 | €14,00 | +21% | BUY |
| SOURCES: DAA, Autohellas | |
Both companies share a common pattern: strong or stable operating activity, "buried" behind increased depreciation arising from their extensive investment programs — €950 million through 2030 for DAA, hundreds of millions of euros annually in fleet renewal for Autohellas.
The difference in our recommendation does not reflect a different view on the quality of the two businesses, but the fact that DAA is already trading close to its determined value, while Autohellas appears to offer a greater margin of safety at its current valuation.
* Director of Research at Solidus Securities S.A., leads portfolio analysis and asset allocation optimization, developing comprehensive financial models for risk assessment and market trend forecasting. President of EEPAMA - HACSA.
** This article is for informational and educational purposes and does not constitute investment, tax, or legal advice. The figures are indicative, based on publicly available historical data, and do not guarantee future returns. Before making any investment decision, consult a certified investment advisor.