Pantelakis Securities maintains an overweight recommendation for Lamda Development with a target price of 8.60 euros per share.
Based on the closing price of 6.60 euros on September 16, this implies a potential return of 30%.
According to analyst Spyros Tsagkalakis, the valuation is derived from the following:
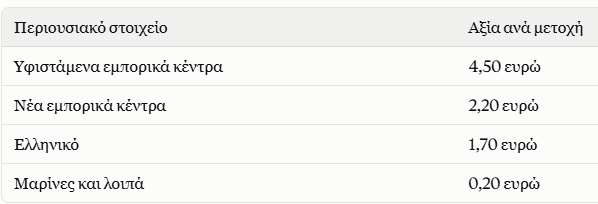
It is noted that the brokerage had reduced the target price to 8.60 euros from 12 euros in May.
Hellinikon in the “red” without land plot sales
As expected, the second quarter was weak, as the comparison with last year was particularly unfavorable. Hellinikon moved to EBITDA losses before valuations of 36.3 million euros, from profits of 47.1 million euros last year. The negative change of 83.4 million euros was slightly larger than the 79.4 million Pantelakis had forecast. The main reason is the absence of land plot sales. Last year, revenues of 66 million euros had been recognized from the Terra Mare transaction, while in the first quarter of 2026 it had revenues of 14 million from Temes.
Hellinikon revenues fell by 50%, to 82.7 million euros. At the gross result level, losses of 14.4 million euros were recorded, slightly better than estimates. Last year gross profit was 65.6 million euros, with a margin of 39.3%. A significant burden was the Riviera Tower. It accounted for 31% of revenues and, according to the brokerage's estimates, recorded a gross loss of about 20 million euros. Little Athens and Cove Residences are estimated to have had a combined gross margin of 10-12%, which was not enough to offset the losses.
According to the analyst, the results show that Hellinikon's profitability depends to a large extent on land plot sales. These have high margins and are recognized as a one-off upon closing of the transaction, resulting in sharp quarter-to-quarter fluctuations.
The group in losses
At group level, EBITDA before valuations turned negative by 12.9 million euros. Last year in the same period the listed company was recording a profit of 69.5 million and in the first quarter of 2026 a profit of 12.3 million. In the half-year the group was essentially at zero (-0.6 million euros), versus 82.1 million last year.
Net losses excluding valuations amounted to 44.8 million euros, more than quadruple the 10.9 million last year. They were also 26%, or 9.1 million euros, higher than estimates. Reported net losses were 23.3 million euros, versus profits of 138.9 million last year. Two opposing valuations contributed to this result:
- negative valuation of 61.7 million euros at Hellinikon,
- positive valuation of 83.4 million in the shopping centers and other properties.
Recovery in malls, pressure on marinas
A positive development was the acceleration in shopping centers. Their EBITDA increased 5%, to 23.9 million euros, 4% above estimates. Golden Hall moved upward to 6.5 million euros and Designer Outlet Athens to 2.8 million. At Lamda Malls level, the increase was limited to 2% (22.1 million euros). The pace was held back by losses of 1.8 million euros from start-up and operating costs for Hellinikon's two new malls.
Marinas EBITDA declined 15%, to 4.5 million euros, mainly due to the expansion works at Agios Kosmas. There, half-year revenues fell 65%, to 1.3 million euros, and EBITDA turned negative by 0.3 million, versus profits of 2.1 million last year. Corfu Marina also recorded losses of 0.5 million euros in the half-year.
Slowdown in collections, reduction in net asset value
Total collections from sales and leases at Hellinikon reached 1.83 billion euros on August 31. Three months earlier they were 1.74 billion and the target for year-end is 2.08 billion. Of the total, 1.31 billion concerns residential properties and 0.52 billion land plots. Second-quarter investments amounted to 155 million euros, bringing the total since the start of the project to 1.27 billion.
Net asset value (NAV) fell 3% since the beginning of the year, to 1.5 billion euros. Per share it stood at 8.81 euros, from 9.06 euros at the end of 2025. At the current price, the stock is trading at a 25% discount to NAV.
In the conference call with analysts, the main issue according to Pantelakis is the timetable and the alternative strategy for the approximately 450 million euro agreement with ION Group, which is delayed.