As many as four rents will be returned by the state, starting tomorrow 25 September and until the end of November, to some of the approximately 50,000 teachers, doctors and nurses serving in the regions and renting a home away from their place of permanent residence.
The first retroactive payment of the support will be made tomorrow, and two more critical dates follow. On Wednesday 30 September, when the deadline expires for corrections of details by tenants, and on 30 November when the process of returning one rent to all beneficiaries (approximately 1 million tenants) will have been completed.
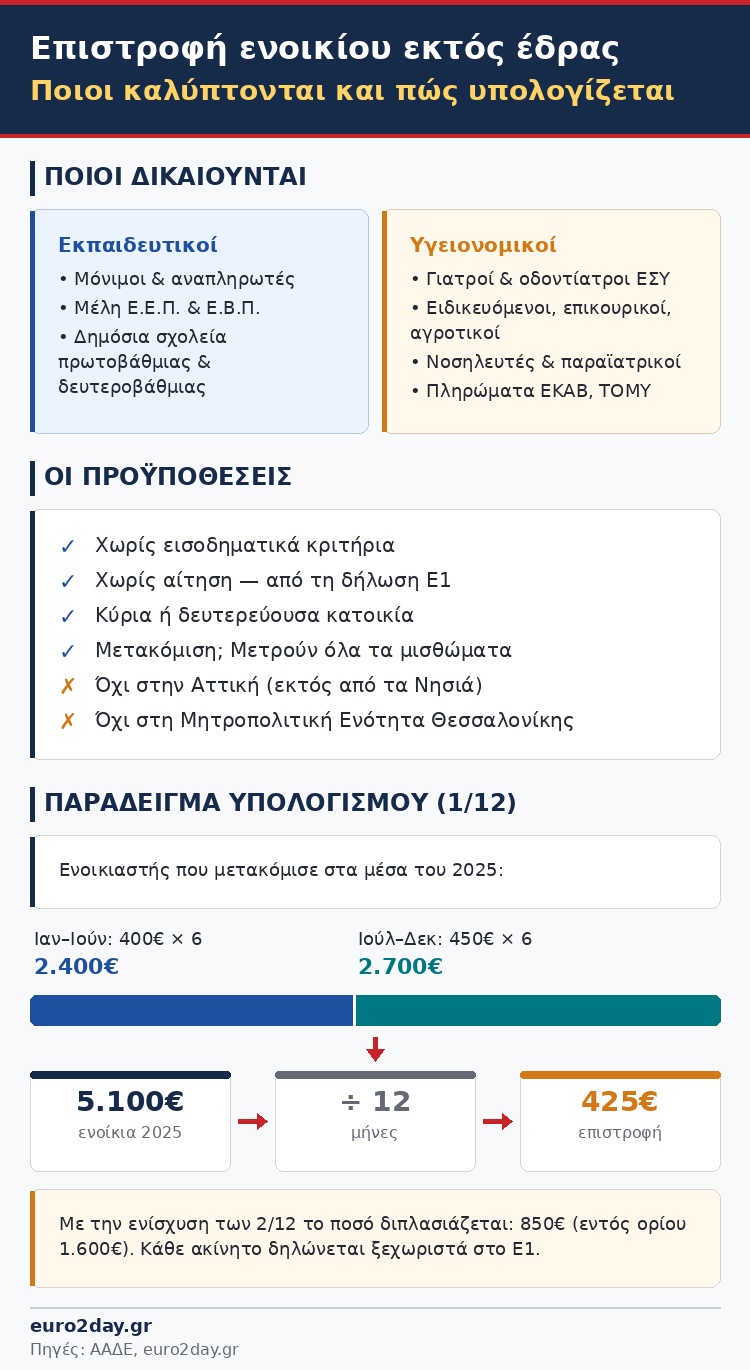
From this autumn - implemented retroactively from 2025 - the new regulation comes into force providing for the return of 2 rents per year without income criteria to the aforementioned categories of workers who serve “away from their base” and rent a primary residence within the region where they serve, outside the Region of Attica - except for the Regional Unit of Islands - and outside the Regional (Metropolitan) Unit of Thessaloniki.
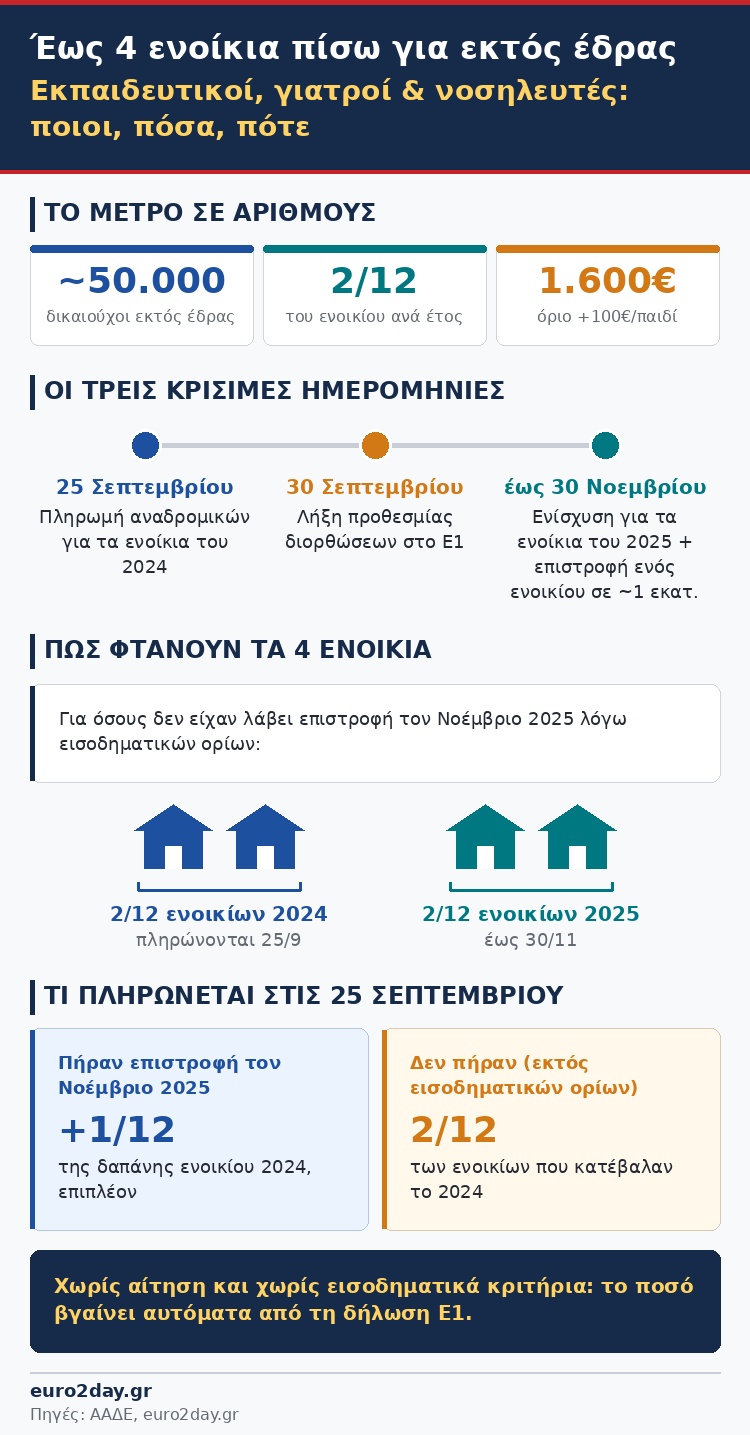
Tomorrow’s payments concern the retroactive amounts for 2025, with beneficiaries divided into two categories:
- Those who received in November 2025 the return of one rent for the rents of 2024, because they met the relevant income criteria, will receive an additional amount equal to 1/12 of the total rent expense of 2024.
- Those who did not receive the refund in November 2025, because they did not meet the income limits, will receive retroactively an amount equal to 2/12 of the rents they paid in 2024.
The rent refund for these specific public officials is carried out without taking income criteria into account.
Subsequently, by the end of November 2026, the support for the rents of 2025 will be paid. As a rule, it corresponds to 2/12 of the total annual rent.
However, when the beneficiary also simultaneously receives the return of one rent for a primary residence, this specific additional support is limited to 1/12, so that in total it reaches two rents.
More specifically, beneficiaries of the support are: teachers, permanent and substitute, as well as members of the Special Educational Staff (E.E.P.) and the Special Auxiliary Staff (E.V.P.) who served for any period during the reference year in public primary and secondary education school units, in areas covered by the measure, as well as medical, nursing and other healthcare staff.
Therefore, under the “umbrella” of the double subsidy are: NHS doctors and dentists, resident and auxiliary doctors, permanent rural doctors, obligated, non-obligated and term personal doctors of public system health hospitals, public units providing Primary Health Care services and the Mental Health Units of the National Network of Mental Health Services as well as doctors providing services within the framework of the operation of the Local Health Units (T.OM.Y.)
Regular and auxiliary nursing staff, staff of the YE branch of Auxiliary Healthcare Staff under the nursing service, paramedical staff, as well as drivers and ambulance crews of EKAV.
Primary or secondary residence
The support is not limited only to cases where the rented property has been declared as a primary residence. It also covers workers who rent a secondary residence in the area where they serve.
From 2025 and for each following year, the financial support corresponds to 2/12 of the total amount of rents paid in the previous year. If within the same year the beneficiary changed residence, the rents paid for all eligible residences are taken into account.
For those who are also entitled to the existing return of one rent, the additional support corresponds to 1/12 of the annual rent.
The support
The total amount of the support cannot exceed 1,600 euros annually for each year of rent payments. The limit is increased by 100 euros for each dependent child of the beneficiary and the spouse. In the event of cessation of marital cohabitation, the increase applies to each of the two parents, while a corresponding provision also applies to parties to a cohabitation agreement.
The calculation of the support is carried out without an application, based on the data of the annual income tax return of the tenant for the respective previous tax year, as it has been formed by the last working day of September of the payment year.
Corrections
The deadline of 30 September concerns exclusively the submission of amended returns by potential beneficiaries, in order to correct errors or omissions in the details of this year’s tax returns, which concern rents paid within 2025, so as to secure the collection of the full amounts of rent refunds to which they are entitled.
These are the codes in table 6 of the E1 form of this year’s tax return, in which the details for rent payments made in 2025 are declared.
The correct completion of the disputed codes will ensure that all beneficiaries receive in full the rent refund amounts to which they are entitled.
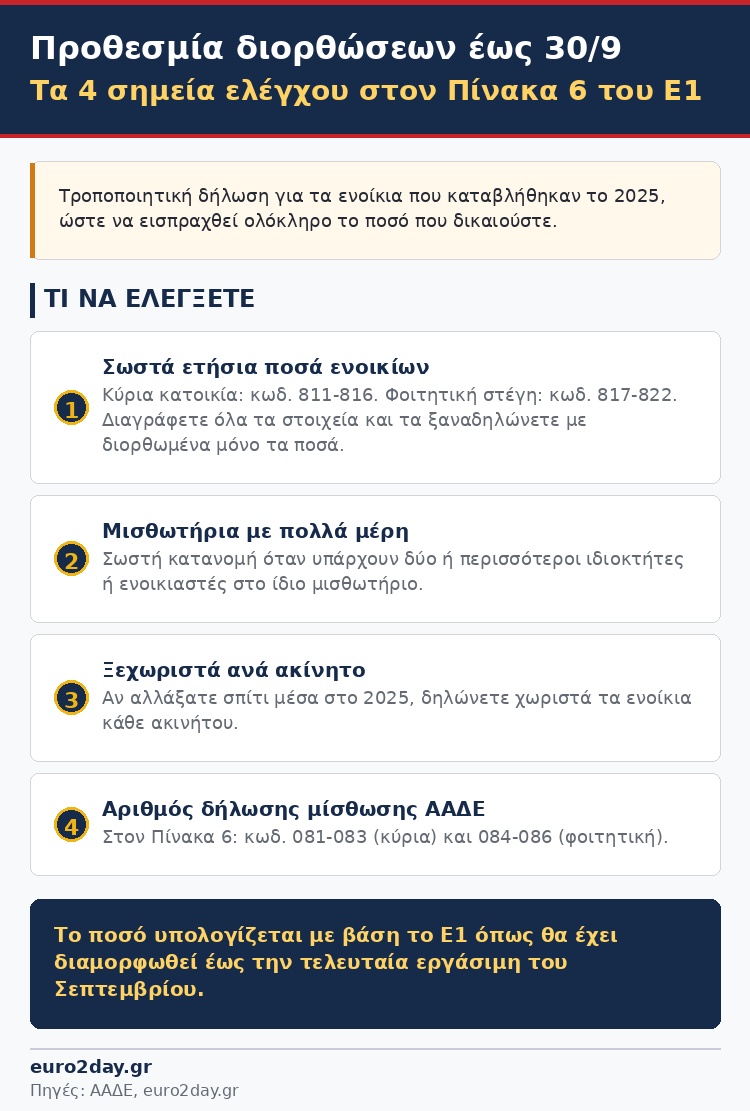
Particular attention should be paid to the following 4 points:
- Correct entry of the annual expense for primary residence rent in codes 811-816 of table 6 of the E1 form and of the annual expense for payment of children’s student housing rent in codes 817-822 of table 6 of the E1 form. Corrections are made by deleting all the details that had initially been entered in table 6 (owner’s TIN, property area, rental months within 2025, electricity supply number, lease number and rent amount) and by re-declaring them with only the rent amounts now corrected, so that the money paid in total in 2025, on an annual basis, for the settlement of primary or student residence rents, as applicable, appears in the corresponding E1 codes.
- Correct entry of the rent expense in cases where leases have been submitted with counterparties being either one owner and two or more tenants, or two or more owners and one tenant, or two or more owners and two or more tenants.
- Correct method of calculating the rent refund. The annual rent expense of the previous year is found from the sum of the rents paid within that year and the amount of the rent refund is calculated at 1/12 of the total annual rent expense. If, for example, from January to June 2025 the monthly rent of the primary residence was 400 euros (a total of 2,400 euros) and from July to December there was a move to a new primary residence, with a monthly rent of 450 euros (a total of 2,700 euros), the total annual rent for the primary residence amounts to 5,100 euros and the rent refund will amount to 425 euros (5,100 euros /12 = 425 euros). In every such case the tenant must declare separately in the E1 return for each property the rents that were paid in total in 2025, in order to receive the full refund to which they are entitled.
- Necessary for each lease is also the declaration of the number of the submitted lease information statement in the corresponding code of table 6 of E1. For each primary residence lease within 2025, the number of the relevant lease information statement submitted to the A.A.D.E. must have been declared respectively in each one of codes 081, 082 or 083 of table 6. Also, for each student residence lease within 2025, the number of the relevant lease information statement submitted to A.A.D.E. must be declared respectively in each one of codes 084, 085 or 086 of table 6.