Greek banks are among those with the greatest sensitivity to interest rates and benefit from higher rates being maintained for a longer period, a UBS report on the sector notes.
We incorporate UBS's estimate for one more ECB interest rate increase of 25 bps in December, to 2.75%, and for a medium-term rate of 2.5% (versus 2% previously in our models), the analysts write.
We are also making other small changes to the modeling, as we upgrade medium-term EPS (FY28E) by 2%-3%. We will further review Q3 as banks publish updates ahead of results, which begin on October 29.
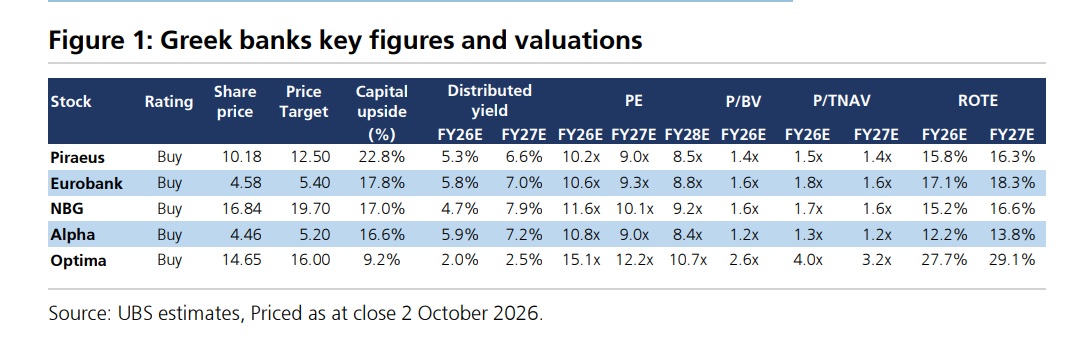
Target prices for the four major banks are increasing by 2%-6%. The house maintains a "buy" rating for all the Greek banks it covers, having recently initiated coverage of Optima (buy, target price €16). Optima is trading at high valuation multiples and, at this stage, we see greater upside potential in the major banks, as shown in the comparison table that follows.
The Euribor rate continued to rise, averaging 2.52% in 3Q26 versus 2.24% in Q2 (+28 bps qoq). For the four major systemic banks, NIMs widen by 2.5 bps to 4.3 bps for every 25 bps increase in Euribor, NII by 1.1% to 1.9% and EPS by 1.5% to 2.5%.
At the initiation of coverage of Optima Bank, the analysts write, we noted that it shows the greatest sensitivity to interest rates among Greek banks (earnings +3.8% for a 25 bps change in interest rates), as it does not have a hedging program and its portfolio consists mainly of floating-rate corporate loans.
As volume growth remains strong, as shown by the European banks' NII tracker that we maintain, the shift in NIM from contraction to mild expansion is likely to lead to strong NII growth in Q3 and for FY26 as well (UBS estimate +10.7% yoy for Alpha, +9.9% for Eurobank, +8% for National and +9.9% for Piraeus). We estimate that Optima will record NII growth of 33% in FY26, as we forecast NII growth of 7% qoq in Q3.
Greek banks have now largely closed the valuation gap versus European banks on a PE basis for FY28E, although the recent decline in valuations due to higher global bond yields has, in our view, highlighted attractive upside potential.
Should they trade at a premium? We believe this is likely, especially as Greek banks are included in developed market indices (MSCI DM by May 2027) and macroeconomic trends remain, in our view, more favorable than in many other European countries.
We see the greatest scope for further re-rating for Piraeus, with our valuation assumptions remaining, in our view, relatively conservative, and with medium-term ROTE upside potential. Alpha is holding a CMD on November 5 in order to present its new medium-term plan, which could act as a catalyst, although it is unlikely to contain a major positive surprise.
The target prices are:
- Piraeus 12.5 euros
- Eurobank 5.4 euros
- National 19.7 euros.
- Alpha Bank 5.2 euros
- Optima Bank 16 euros