Retail bank lending rose by 9.8% in the first nine months compared with the same period last year. Mortgages saw the strongest growth. Consumer lending also performed well, while loans to small businesses fell.
Across the three retail categories, total loans worth €5.16bn were issued from January to September 2026.
Mortgages
According to information obtained by Euro2day.gr, more than 40,000 mortgages worth about €2.2bn were issued in the first nine months, up 25.5% on the €1.740bn in loans granted in the same period of 2025. In effect, nearly €500m more was lent in mortgages in the space of a year.
It is worth noting, however, that the high growth rate is also due to mortgages starting from a lower base than other retail loan categories.
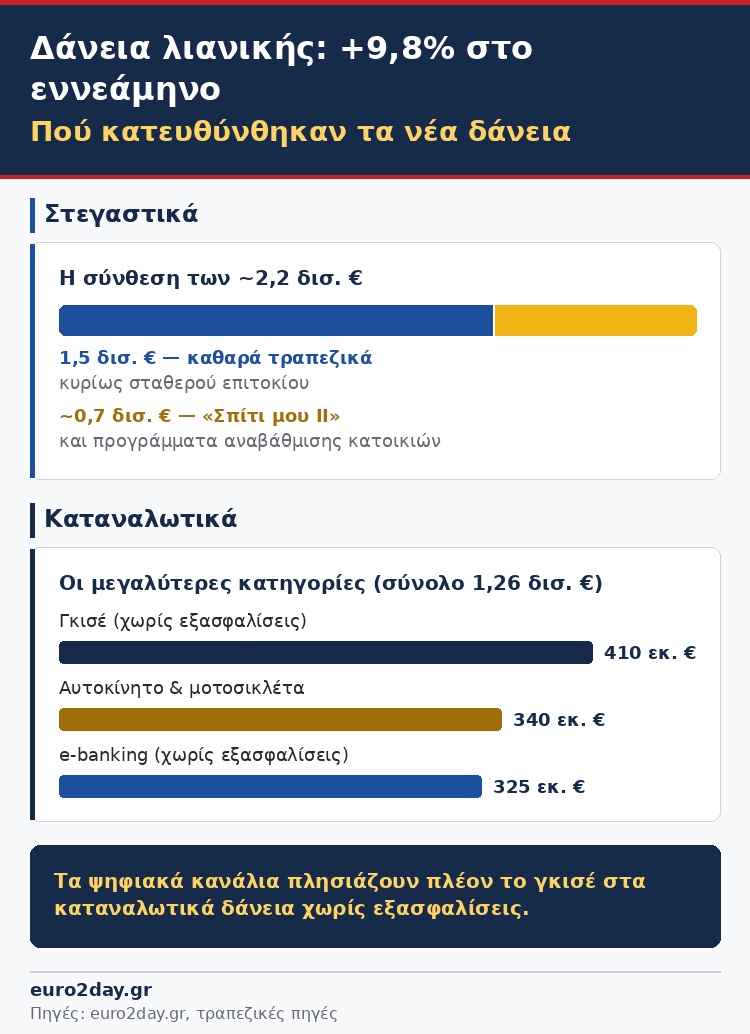
The composition of this lending is also noteworthy: of the approximately €2.2bn, €1.5bn was in conventional bank mortgages, mainly at fixed rates, while the remainder was linked to the “My Home II” programme and home renovation schemes.
Consumer loans
Consumer credit continued its positive trend in the first nine months of 2026. It is worth noting that demand for consumer loans began rising before demand for mortgages. Across the market, about 310,000 new loans worth €1.26bn were issued from January to the end of September this year.
Lending rose by 7.2% compared with the same period last year, when loans worth €1.170bn were issued. Among the qualitative trends, one notable development was the increase in unsecured consumer loans taken out through e-banking (the banks’ digital channels), with the amount reaching €325m.
Traditional over-the-counter lending “generated” €410m in unsecured consumer loans in the first nine months. Demand for consumer loans to buy cars and motorbikes also remained strong, with lending in the first nine months totalling €340m.
Small businesses
The picture is different, according to the same sources, for lending to micro and small businesses, which are classified as retail. Lending to companies with turnover of up to €2.5m and a loan size of €1m was down 3.9%. Disbursements totalled €1.7bn, covering about 26,000-27,000 cases.
In the same period last year, loans worth €1.77bn were issued.
Banking sources attribute the slowdown in lending to the challenging mix of factors that has emerged, linked to rising energy costs combined with higher interest rates.