DIMAND is going through a period of intense development activity, with the maturation of its investment portfolio reflected both in its financial results and in its expanding prospects. In the first half of 2026, the company recorded a significant increase in profitability, while its portfolio grew, with total estimated gross development value (GDV) reaching about €2.2bn and net asset value (NAV) standing at €240.1m.
Behind the figures is a strategy that combines the development of complex urban regeneration projects, the exploitation of properties with significant potential for value appreciation, and partnerships with leading business groups. From Cambas Estate and the new bioclimatic office complex on Mesogeion Avenue to the development of the complex in Eleonas for HEDNO, DIMAND aims to turn investment opportunities into projects with long-term economic and development value.
In the following interview, Anna Chalkiadaki, DIMAND’s CFO, discusses the company’s first-half performance, its priorities through the end of 2026 and the group’s prospects, explaining how disciplined execution of its strategy can strengthen the creation of sustainable shareholder value.
The first half of 2026 was marked by a significant improvement in profitability, with operating profit up 19.3% and pre-tax profit up 53.6%. What were the main drivers of this performance, and how sustainable do you consider this momentum?
The strong first-half performance reflects progress in executing and maturing our investment portfolio. Revenue reached €66.0m, up from €27.4m, driven by increased activity and progress on projects under way. Operating profit came to €17.1m, while pre-tax profit attributable to DIMAND shareholders was €22.7m, compared with €14.4m and €14.8m, respectively, in the first half of 2025. The larger increase in pre-tax profit also reflects the positive contribution of our joint ventures.
We believe the conditions are in place for this positive trend to continue, as our portfolio includes a significant number of projects with end-users or buyers already secured, while scheduled completions and divestments over the coming years improve the visibility of future results. At the same time, recycling capital from divestments supports the ongoing renewal and growth of our portfolio.
Of course, given the nature of our business, financial results are affected by the time it takes for individual projects to mature and be completed, and may therefore fluctuate between reporting periods. What matters more to us is the creation of value over time, as reflected in the development of the company’s net asset value (NAV).
Management has said it expects even stronger results for 2026 as a whole, taking into account agreements and transactions completed after the first half. What can we expect in the second half, and what are the main milestones through the end of the year?
The second half began with a significant agreement with HEDNO reached in late July, which confirms our ability to undertake and deliver complex, large-scale projects. It includes the sale of the office complex under development in Eleonas for €134.7m. The project has a buyer secured while still at the development stage, with payments made in instalments. This limits commercial risk and helps fund its development.
We are focused on three milestones through the end of the year. First, progressing our projects according to schedule, including the new Piraeus Court Complex, whose first buildings were handed over in July. Second, completing the divestments planned for 2026, above all DI Terna (an office building in Marousi).
Third, starting or accelerating work on new projects, such as FIX in Thessaloniki, where we have signed a long-term management agreement with Hilton, and the Mesogeion campus with PPC. These developments strengthen our expectations for a positive trend in financial results for 2026 as a whole, while laying a strong foundation for the further growth of the DIMAND group.
DIMAND’s portfolio has grown to 16 projects, while total GDV has surged to €2.19bn from €1.36bn at the end of 2025. What comes next: further expansion of the portfolio or a greater focus on maturing and realising value from existing investments?
Our priority for the coming period is to execute and mature our existing portfolio effectively. The increase in GDV to €2.19bn is mainly due to major strategic additions, such as Cambas Estate and the Mesogeion complex. Our strategy is now focused on systematically advancing these projects, from permitting and financing through construction and completion to their eventual realisation.
At the same time, we continue to assess new investment opportunities, focusing on their potential to generate value, expected returns relative to the risks involved, and the efficient allocation of available capital. Capital recycling through divestments is particularly important to us, as it helps fund new projects. In practice, the portfolio will continue to be renewed: projects will be completed and sold, while new ones are added. Our aim is to grow the portfolio in a balanced way, with an emphasis on investment quality, efficient use of capital and maintaining a sound capital structure.
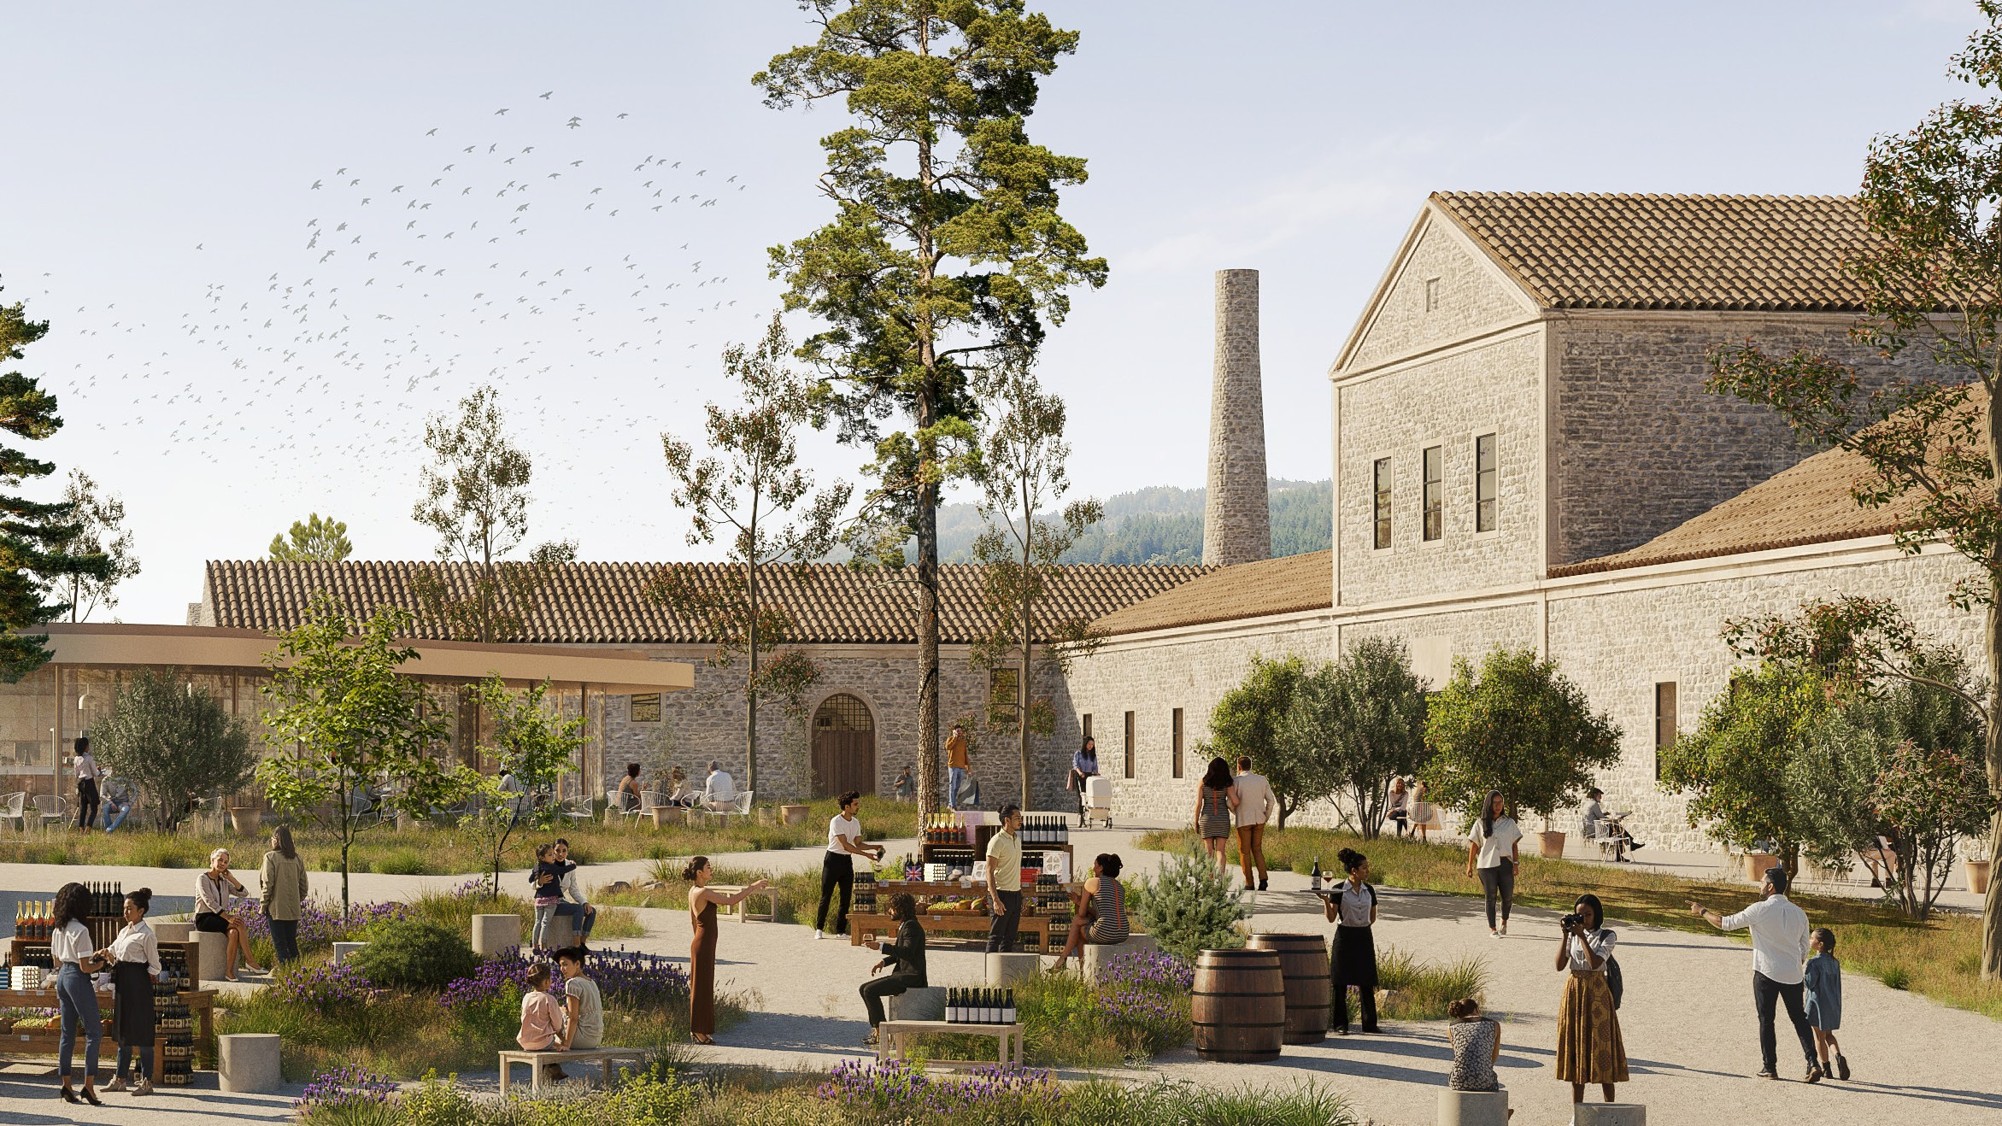
Cambas Gardens – UNS
The acquisition of Cambas Estate and the partnership with PPC on the new bioclimatic complex on Mesogeion Avenue are two significant moves. What do they add to DIMAND’s portfolio strategically, and what do you look for today in a new investment or strategic partnership?
The two moves are significant strategic investments with different characteristics that strengthen and diversify our portfolio. Cambas Estate, covering about 315 hectares in Mesogeia, is one of the few landholdings of this size near Athens. It offers considerable potential for a mixed-use development in an area with a strategic location and strong growth prospects. Our aim is to make the most of the property’s distinctive features, creating a project that adds value both for the company and for the wider area.
Our partnership with PPC, through the joint venture Powerhub Properties, is focused on developing a modern office complex. It combines DIMAND’s property development expertise with the strategic presence of a major business group. It is also a good example of our approach to developing modern, sustainable office buildings, with the aim of achieving LEED and WELL Platinum certifications.
When assessing a new investment, we focus primarily on its potential to generate significant added value, the prospects for commercial use of the property and the expected return on investment relative to the risks and capital required. In a partnership, we look for partners with a shared strategic outlook and the ability to make a meaningful contribution to the successful delivery and realisation of projects.
Increased investment activity has been accompanied by a rise in net debt to €80.4m and in net LTV to 32%, from 24% at the end of 2025. How much headroom does DIMAND have to increase leverage and fund its next phase of growth without weakening its strong capital base?
The increase in borrowing has gone hand in hand with the progress of our investment programme. It reflects both new investments, such as Cambas Estate, and the capital needs of projects in development and construction. At the end of the first half of 2026, net debt stood at €80.4m and cash at €58.1m. Net LTV was 32%, a level we consider manageable and consistent with our financial strategy. Our capital structure, together with expected divestments and project-specific financing, gives us the flexibility we need to support our investment programme.
We manage leverage by financing individual projects according to their specific characteristics and cash flows, as well as by gradually releasing capital through divestments. In addition, agreements with buyers secured in advance and scheduled instalment payments, as in the case of HEDNO, help limit funding requirements during construction.
It is natural for the leverage ratio to fluctuate depending on the stage of development and completion of projects. Our key priority remains maintaining a balanced capital structure that supports our growth while safeguarding the financial stability of the DIMAND group.
NAV has already risen to €240.1m, while the portfolio’s GDV stands at about €2.2bn. What is DIMAND’s biggest challenge today: continuing to grow the portfolio or more effectively translating this growth momentum into value that is also recognised in the company’s market valuation?
Our priority is not simply to further expand the portfolio, but above all to realise its value effectively and create substantial, sustainable value for our shareholders. The increase in GDV reflects the growth prospects of our portfolio, but the success of our strategy is measured by projects maturing, successful divestments being completed, and cash flows and investment returns being generated.
NAV stood at €240.1m, compared with €217.5m at the end of 2025 and €125.5m at the end of 2022, when DIMAND listed on the stock exchange. This increase reflects the significant progress made in developing the portfolio and creating value through our investment activity.
We believe that consistently executing our business plan, successfully completing projects and divestments, and keeping the investment community informed transparently and systematically are the most important factors in bringing DIMAND’s value to light.
At the same time, analyst coverage raises the company’s profile and helps the investment community understand our business model. We remain focused on creating long-term value for our shareholders, and believe that delivering our strategy will gradually help the market better recognise the company’s prospects.
Pantelakis Securities recently initiated coverage of DIMAND shares with a ‘Buy’ recommendation and a €17 target price, implying upside of about 31%. What are the key features of DIMAND’s strategy and investment portfolio that can support further shareholder value creation in the coming years?
Analysts’ estimates and target prices are independent assessments and, as such, we do not comment on them. However, we see Pantelakis Securities’ coverage of DIMAND as very positive, as it helps the investment community better understand our business model, strategy and growth prospects.
DIMAND’s ability to create value for shareholders rests on several key competitive advantages. First, our existing portfolio provides significant visibility, as several of our projects already have end-users or buyers secured, limiting commercial risk. At the same time, our presence across different property sectors, including offices, hospitality, logistics and residential, provides diversification and opportunities to capitalise on prospects in different parts of the market.
Our expertise in developing and regenerating complex properties, and in delivering projects to high sustainability standards, is also particularly important. Through this work, we aim to create significant added value. Finally, our financial strategy plays a key role, based on disciplined capital allocation, recycling capital through divestments and developing strategic partnerships.
We believe that combining these strengths with the successful execution of our investment programme creates strong conditions for further growth and long-term value creation for our shareholders.