At a glance
| Share | Price on 9 Nov (€) | Fair value (€) | Upside/downside | Downside | Base | Upside | Weighted (€) |
|---|
| OTE | 18.70 | 19.75 | +6% | 17.2 | 20.7 | 23.1 | 20.6 |
| Coca-Cola HBC (EEE) | 51.00 | 45.10 | −12% | 38.3 | 50.2 | 59.1 | 48.8 |
The price is the closing price on the Athens Stock Exchange on Monday, 9 November 2026. Fair value is our weighted estimate. The three scenarios are 12-month price targets, and the final column shows their weighted average.
OTE
OTE closed at €18.70 (−0.43% on Monday). With 388.2m shares outstanding (394.2m in total less about 6.0m treasury shares), its market capitalisation is €7.26bn. Adding net financial debt excluding leases (€466m) gives an enterprise value of €7.73bn. We use debt excluding leases because EBITDA after leases (AL) already includes their cost.
For 2026E, we assume adjusted EBITDA AL of €1,412m: €1,053.1m for the first nine months and about €359m in the fourth quarter, implying growth of 2% against a high base, as management itself has warned. We estimate adjusted net profit at about €659m (€488.9m for the first nine months and about €170m in the fourth quarter, our assumption), implying EPS of about €1.69.
Underlying free cash flow is €575m, at the midpoint of management’s target (€570m–€580m). At the current price, the shares trade at 11.0x P/E and 5.5x EV/EBITDA AL, with an underlying cash flow yield of 7.9%. The €0.90214 dividend represents a yield of 4.8%, while the total distribution of €532m is equivalent to about 7.3% of market capitalisation.
Fair value
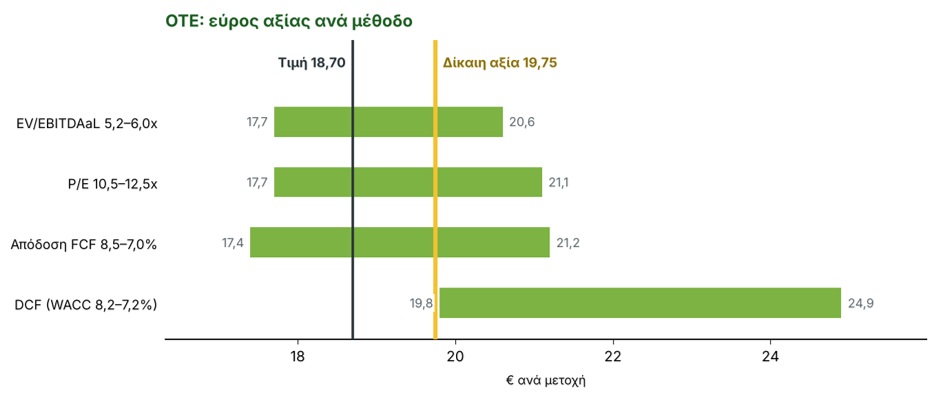
Fair value comes to €19.75, 5.6% above the share price. The low end of the first three methods is close to €17.5, about €1.2 below the share price. The stock therefore offers little margin of safety, but does provide a steady distribution yield.
DCF is the most optimistic method and has the lowest weighting (15%). It uses cash flow of €545m (€575m less €30m for spectrum in 2027), growth of 2.5% for five years and terminal growth of 1.0–1.5%.
| Method | From (€) | To (€) | Average (€) | Weight |
|---|
| EV/EBITDAaL 5.2–6.0x | 17.7 | 20.6 | 19.2 | 35% |
| P/E 10.5–12.5x | 17.7 | 21.1 | 19.4 | 30% |
| FCF yield 8.5–7.0% | 17.4 | 21.2 | 19.3 | 20% |
| DCF (WACC 8.2–7.2%) | 19.8 | 24.9 | 22.4 | 15% |
| Fair value | | | 19.8 | 100% |
12-month price-target scenarios
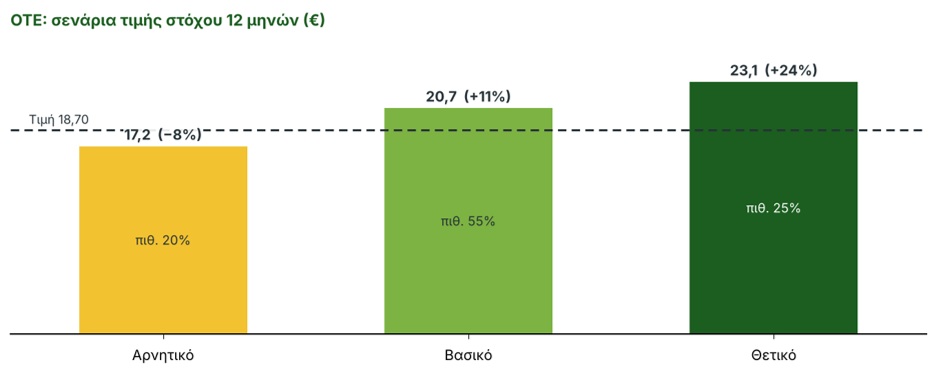
The scenarios are based on 2027E EBITDA AL, net debt excluding leases at the end of 2026, and an EV/EBITDA AL multiple. Net debt depends on the fourth quarter: meeting the full €750m target requires free cash flow of about €403m, while underlying cash flow of €223m–€233m is needed.
| Scenario | 2027E EBITDA AL (€m) | EV/EBITDA AL | 2026E net debt (€m) | Target price (€) |
|---|
| Downside | 1,412 | 5.0x | 400 | 17.2 |
| Base | 1,447 | 5.7x | 220 | 20.7 |
| Upside | 1,468 | 6.2x | 120 | 23.1 |
In the downside scenario (20%), EBITDA AL remains flat, fourth-quarter cash flow is limited to the underlying level, the slowdown in mobile service revenue continues, and the multiple falls to 5.0x. In the base case (55%), EBITDA AL grows by 2.5% and the multiple rises to 5.7x, below the 6x level we consider typical of European peers. In the upside case (25%), growth reaches 4% and the multiple 6.2x.
| Scenario | Probability | Target price (€) | Vs. current price |
|---|
| Downside | 20% | 17.2 | −8% |
| Base | 55% | 20.7 | +11% |
| Upside | 25% | 23.1 | +24% |
| Weighted | 100% | 20.6 | +10% |
What we are watching from here
- Mobile service revenue, which has slowed from +5.5% to +2.0% over the course of the year.
- Working capital: trade receivables are up 23% since December, owing to IT projects.
- The timing of taxes, which boosted third-quarter cash flow.
- The cost of spectrum renewal in 2027, which the market expects to be covered by Romania’s tax benefit.
Coca-Cola HBC (EEE)
EEE closed at €51.00 (+2.72%), following Thursday’s 14.1% fall and Friday’s 1.68% decline. Its market capitalisation is €18.52bn and its enterprise value €19.75bn. Based on 2026E estimates, the shares trade at 17.8x P/E and 10.2x EV/EBITDA, with a cash flow yield of 4.1%.
Fair value
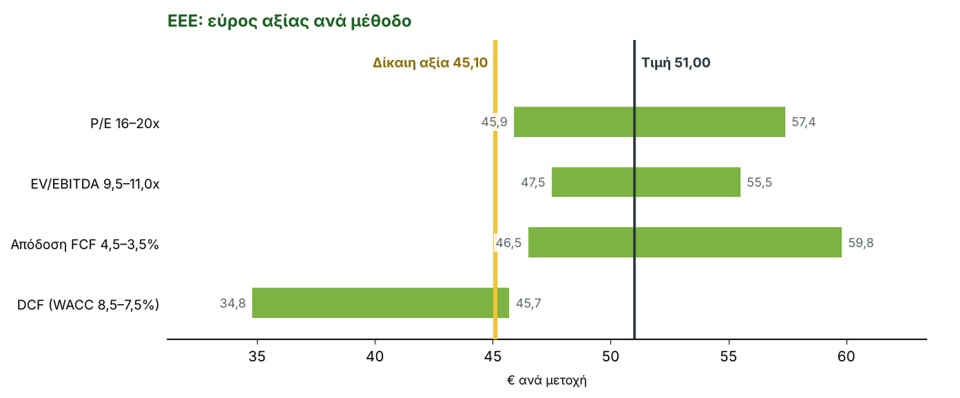
The valuation depends on two scenarios. If Russia remains under the group’s control, the four methods give a weighted value of €49.6. If control is lost, we deduct about €390m from EBITDA, apply a 9.5x multiple and add Russia’s cash to net debt (more than €1bn, or about €2.8 per share): the value falls to €34.5. If Russia is lost but the cash is retained, the value is €40.5. Assuming a 30% probability of losing control (no decision has been announced), fair value is €45.10, 11.6% below the share price.
The conclusion is that, despite a fall of about 13% from pre-announcement levels, based on our valuation ranges the share price is pricing in Russia’s full retention.
We do not share the view that the worst-case scenario is already priced in: it implies a value of about €34.5, or roughly 32% lower. Before the news, the shares (€58.8) traded at more than 20.5x P/E, above our valuation range.
| Method | From (€) | To (€) | Average (€) | Weight |
|---|
| P/E 16–20x | 45.9 | 57.4 | 51.7 | 30% |
| EV/EBITDA 9.5–11.0x | 47.5 | 55.5 | 51.5 | 30% |
| FCF yield 4.5–3.5% | 46.5 | 59.8 | 53.1 | 20% |
| DCF (WACC 8.5–7.5%) | 34.8 | 45.7 | 40.3 | 20% |
| Fair value | | | 45.1 | 100% |
12-month price-target scenarios
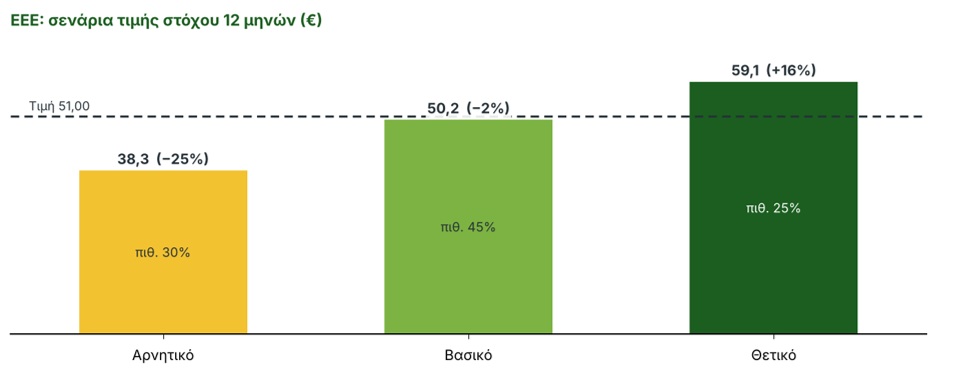
For 2027E, we assume EBIT growth of 8% (at the lower end of the mid-term framework), EBITDA of €2,073m, of which about 20% (€416m) comes from Russia (€390m out of €1,945m in 2026E). Net debt at the end of 2026 is estimated at €833m (€1,233m less free cash flow of €760m plus an estimated dividend of about €360m). CCBA is excluded.
| Scenario | Assumption | Target price (€) |
|---|
| Downside (30%) | Loss of control of Russia and its cash; 9.5x 2027E EBITDA excluding Russia | 38.3 |
| Base (45%) | Russia remains, valued at 5.0x; the rest at 10.25x | 50.2 |
| Upside (25%) | Russian risk eases; 10.75x 2027E EBITDA | 59.1 |
| Scenario | Probability | Target price (€) | Vs. current price |
|---|
| Downside | 30% | 38.3 | −25% |
| Base | 45% | 50.2 | −2% |
| Upside | 25% | 59.1 | +16% |
| Weighted | 100% | 48.8 | −4% |

What we are watching from here
- Any decision or announcement concerning Multon and Multon Partners.
- The company’s analysis of how much of Russia’s cash is included in net debt.
- The fourth quarter: guidance implies organic revenue growth of about −0.5% to +1.7%, with four fewer selling days.
- Completion of CCBA by the end of 2026 (Tanzania remains outstanding).
Assumptions and limitations
The valuation calculations, scenario probabilities and 2027E assumptions are our own. Probabilities are estimates, not measurements, and the weighted price changes by about €0.3–€1.6 per share if probability shifts by five percentage points between the downside and upside scenarios.
* Director of Research at Solidus Securities ΑΕΠΕΥ, overseeing portfolio analysis and asset-allocation optimisation and developing integrated financial models to assess risk and forecast market trends. President of EEPAMA - HACSA.
** This article is for information and educational purposes only and does not constitute investment, tax or legal advice. The figures are indicative, are based on publicly available historical data and do not guarantee future returns. Before making any investment decision, consult a certified investment adviser.