JP Morgan expects Greek banks to maintain steady operating momentum, but sees profitability edging down from the highs of the second quarter.
The US bank has published its preview of third-quarter 2026 results. Analysts Mehmet Sevim and Anna Zaslavskaya updated their models after meetings with bank management teams. Price targets are unchanged and are set for December 2028:
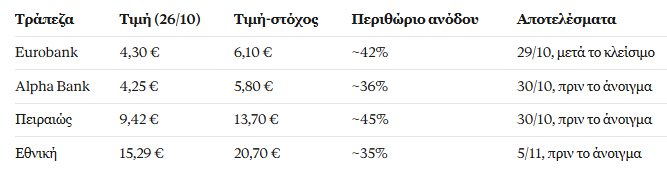
The quarter follows a clear common pattern. Net interest income rises by 3% to 5% quarter on quarter, driven by credit expansion, with loans growing by around 1% during the quarter. By contrast, fees and trading income fall from their high second-quarter base. The cost of risk also edges up at most banks.
Eurobank: €419m in profits
JP Morgan forecasts net profit of €419m for Eurobank, down 2% quarter on quarter. Reported net profit rises 1% to €409m, with return on tangible equity (RoTE) at 16.8%, down from 17.2%.
- Net interest income: +3%, with loans up 1% quarter on quarter and 8% year on year. The net interest margin falls by 3 basis points to 2.46%.
- Fees: +3%.
- Operating expenses: +1%, with the cost-to-income ratio steady at 35.7%.
- Cost of risk: 54 basis points, up from 51 basis points.
- One-offs: Restructuring costs of €10m.
- CET1: 15.3%.
For 2026, the bank raises its estimate for adjusted earnings by 2% to €1.62bn. JP Morgan expects Eurobank to deliver the highest “normalised” return in the sector, at more than 17% in 2028. The shares are up 26% since the start of the year. They trade at 7.9 times 2028 earnings and 1.3 times tangible book value.
Alpha Bank: Donation weighs on quarter; Investor Day in focus
JP Morgan forecasts net profit of €257m for Alpha Bank, down 4% quarter on quarter. The result is weighed down by an annual donation of €25m to renovate schools, which most of its peers will record in the fourth quarter. Reported RoTE is estimated at 9.8% and adjusted RoTE at 11.4%.
- Net interest income: +3%, with the margin steady at 2.17%.
- Fees: Down 17% to €155m. Second-quarter fees were boosted by the Prodea dividend. On an underlying basis, fees rise 6%.
- Trading and other income: Recovers to €23m from €4m.
- Cost-to-income ratio: Improves to 38%.
- Cost of risk: Rises to 44 basis points from 39 basis points.
- NPE ratio: Falls to 3.4%.
- CET1: Steady at 14%.
The shares are up 19% since the start of the year and trade at 8 times 2028 earnings and 1 times tangible book value, the lowest valuation in the sector. The key catalyst is the Investor Day on 5 November. The event is expected to provide clarity on the bank’s strategy and targets, as well as the benefits of its partnership with UniCredit. JP Morgan sees Alpha’s return reaching around 13.5% in 2028.
Piraeus: Higher provisions and a small trading loss
JP Morgan forecasts net profit of €313m for Piraeus, down 7% quarter on quarter. Reported net profit comes to €315m, with RoTE at 15.2%, down from 16.7%.
- Net interest income: +5% to €533m. The margin rises to 2.32%.
- Service income: Down 14% to €216m.
- Trading: A loss of €5m due to volatility in bond markets.
- Operating expenses: Down 3% from the high second-quarter base, reflecting variable pay. The cost-to-income ratio rises to 32%.
- Cost of risk: 65 basis points, up from 57 basis points. The bank is proactively strengthening its balance sheet, in line with its revised guidance.
- CET1: 12.9%.
For 2026 as a whole, the estimate for adjusted earnings is cut by 3% to €1.27bn, due to lower trading income and higher provisions. Piraeus is the best-performing share this year, up 39%. However, it remains the cheapest on a P/E basis, at 7.6 times 2028 earnings. Ethniki Insurance is seen as key to the investment case, with its contribution in the first half running ahead of its full-year target.
National Bank of Greece: Steady profits and around €1bn in excess capital
JP Morgan expects net profit of €308m at National Bank of Greece, virtually unchanged quarter on quarter. Reported profit rises 4%, reflecting a smaller impact from one-off items. RoTE is estimated at 13.4%, down from 13.9%.
- Net interest income: +4% to €577m. The margin rises by 5 basis points to 2.73%.
- Loans: Up 1% quarter on quarter and 12% year on year, the fastest rate in the sector.
- Fees: Down 6%, reflecting the high second-quarter base from Recovery Fund loans and strong capital markets activity.
- Trading: €12m, down from €18m.
- Operating expenses: +4%, with the cost-to-income ratio at 37.1%.
- Cost of risk: 37 basis points.
- NPE ratio: 2.3%.
- CET1: 17.2%, the highest in the sector.
JP Morgan notes that management has indicated fees could slightly exceed its target of “mid-single-digit” growth in 2026. Market consensus puts growth at 9%. For 2026, the estimate for adjusted earnings is cut by 3% to €1.28bn, mainly due to lower trading income.
According to JP Morgan, National Bank trades at a premium to the sector. However, it has around €1bn in excess capital, leaving room for higher distributions. Deploying this capital could trigger the next leg of a re-rating in the shares. Risks identified by the bank include a potential sale of the Hellenic Financial Stability Fund’s remaining 8.39% stake. The shares are up 18% since the start of the year, and trade at 8.4 times 2028 earnings.