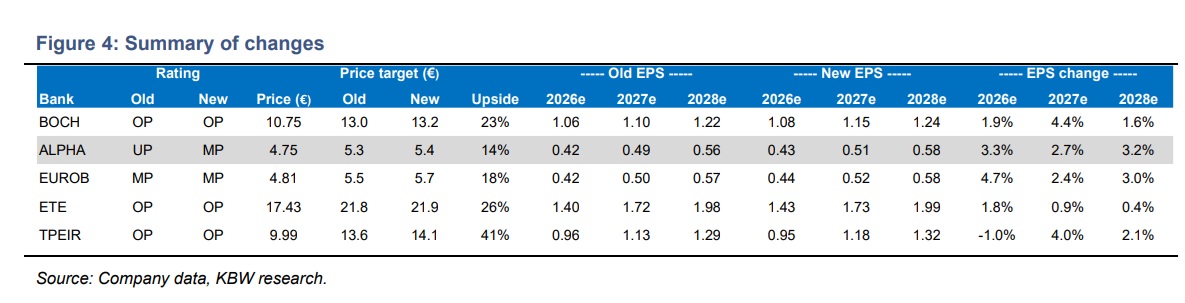
KBW’s analysis of the domestic banking sector points to a positive quarter, with results generally beating expectations and management guidance revised upwards.
“We upgrade Alpha Bank to Market Perform (M/P) from Underperform (U/P) following its Investor Day, at which credible targets were announced,” the analysts write.
Although the target of a 14.5% RoTE in 2028 does not justify the higher 2028 P/E multiple implied by consensus estimates compared with Piraeus and Eurobank, which are already recording returns (RoTE) of around 15%-19%, the bank is delivering strong growth, supported by a favourable macroeconomic environment. The price target, which implies upside of around 14%, values the bank at just 9.4 times estimated 2028 earnings (P/E).
“We continue to prefer National Bank, Piraeus and Bank of Cyprus, given their greater sensitivity to interest rates and the higher returns they offer shareholders,” the analysts write. They maintain their M/P recommendation on Eurobank, despite its attractive growth and profitability, as it continues to have the largest exposure to term deposits in Greece and, in their view, shows weaker efficiency performance.
We raise our estimates by around 2%-5% and remain positive on the sector, with Greek banks trading at a discount of around 17% to domestic Spanish banks.
PIRAEUS (Outperform recommendation)
Positive operating trends were overshadowed by higher-than-expected provisions, linked to the reclassification of certain NPEs. However, guidance for the cost of risk (CoR) was reaffirmed at around 60 basis points, with management noting that the decision was taken to lay the foundations for 2027, which “is proving to offer significant upside surprise potential”.
Estimates are now based on the assumption that the ECB interest rate will be 3.0% in 2027, supporting net interest income (NII) as a share of assets at above 2.4%, compared with the target of around 2.2% for 2026. The integration of Ethniki Insurance also appears to be progressing faster than expected.
NATIONAL BANK (Outperform recommendation)
The loan book continues to grow at a low double-digit rate year on year, supporting 6% quarter-on-quarter growth in net interest income (NII) and a RoTE of 15.7% (20.7% adjusted for excess capital).
Fee income is also continuing to grow at a double-digit rate year on year, while the CET1 ratio remains strong at 17.5%. The bank now sees scope to exceed its forecasts for NII and RoTE, but will provide more detailed targets when it updates its business plan in February.
| Bank | Recommendation | Price (€) | Target (€) | Upside | 2028 P/E | 2028 RoTE |
|---|
| Piraeus | Outperform | 9.99 | 14.1 | 41% | 7.6 | 17.8% |
| National Bank | Outperform | 17.43 | 21.9 | 26% | 8.8 | 19.8% |
| Bank of Cyprus | Outperform | 10.75 | 13.2 | 23% | 8.7 | 20.0% |
| Eurobank | Market Perform | 4.81 | 5.7 | 18% | 8.2 | 18.6% |
| Alpha Bank | Market Perform ▲ | 4.75 | 5.4 | 14% | 8.2 | 14.3% |
▲ Upgrade from Underperform. Prices as of 11 November 2026. Source: KBW (Stifel).
BANK OF CYPRUS (Outperform recommendation)
Profits were boosted by reversals of previous provisions. However, underlying revenue came in above consensus estimates, while volume growth was better than expected.
The CET1 ratio remains particularly strong at 20.3% (on a pro forma basis, taking into account the recent transaction with CDB), while NII guidance was revised upwards. The bank also expects RoTE to be close to 20% this year, compared with its previous forecast of around 15%.
EUROBANK (Market Perform recommendation)
The bank reported quarterly RoTE of 17.8%, supported by strong loan growth in Bulgaria (+17% year on year) and an acceleration in credit expansion in Cyprus (+7% year on year).
Guidance for this year’s NII was also revised upwards, to +9% from +7%, though it remains, in our view, conservative. Fee income continues to grow at a satisfactory pace and is expected to receive a significant boost from the consolidation of Eurolife, which is estimated to contribute €20-25 million in the fourth quarter.
ALPHA BANK (upgraded to M/P)
A positive quarter, with NII up 8% quarter on quarter. “We view the focus on volume growth, rather than the adoption of aggressive interest rate assumptions, positively,” the analysts note.
At the same time, the “capacity for distributions” of more than €4 billion reflects the potential returns the bank could offer shareholders. However, cash distributions remain relatively low, while a 20-basis-point compression in the interest margin over four years could be considered an optimistic assumption.